The original article is from Saurabh Deshpande
Compiled by | Express Man@Odaily Planet Daily

I have been thinking about a question: since perpetual futures (perp, short for perpetual futures) are already so easy to use, why does the crypto market still need options. I keep coming back to the same answer—time. You may think Bitcoin will be higher in three months, but a leveraged perp could be liquidated tomorrow. Buying a call option gives your judgment more room to breathe. You can still lose everything you paid, but one bad afternoon will not force you out of the position.
This leads us to ask: why are on-chain options still so small to this day. We tried to buy them several times, checked liquidity, and looked at why so many previous attempts failed. Most of the reasons ultimately come down to the same thing—whether selling options is worth the trouble. Perp exchanges may change this, because they can give sellers a place to hedge and also bring sellers traders who are already there. This article is about: why this could work, what remains unresolved, and who would benefit. We will also explore several designs that can provide incentives to sellers.
Over the past few weeks, I have been playing Papertrade. On this platform, the house takes the opposite side of every trade, and for every $1 you lose, a corresponding amount of PAPER is minted—this token can share in a portion of the house's fee revenue. The practice of compensating losses with tokens made me think: what it would look like if this were applied to options, because this category has not yet produced an explosive success story.
A perp lets you choose how far the price can move against you. It never lets you choose how long you can be wrong. Options can. In July 2025, we argued in an article that options would follow perps on-chain and could grow a hundredfold in three years. Fifteen months later, options are still less than 1% of perp DEX volume. In traditional markets, options volume is about three times that of futures.
This is another article in a series about the current state of crypto options.
In this piece, I quantified the cost a perp imposes on a trader who is "right but early"; explained why the next wave of on-chain options will grow next to perp markets like Hyperliquid; took stock of who is doing what; and which protocols benefit most once volume really picks up. The short answer is: whoever controls hedging benefits. The three positions worth holding are—Hyperliquid as the landlord of the hedging market, Derive as the engine others build on, and Paradex as the counter for block trades. Then we outlined two projects that could bring in the missing sellers.
One puts options into Metric's LP pool, and the other is an options version of Papertrade.
Right Direction, Wrong Route
How often does a perp kill a trade that should have been profitable? We took BTC's daily closing prices from January 2018 to October 2026, treating every day as a possible long entry point. We kept only those trades that closed above the entry price after 7 to 180 days—that is, the ones where the trader was right—and then checked whether BTC during the holding period fell enough to liquidate a 5x, 10x, or 20x perp.
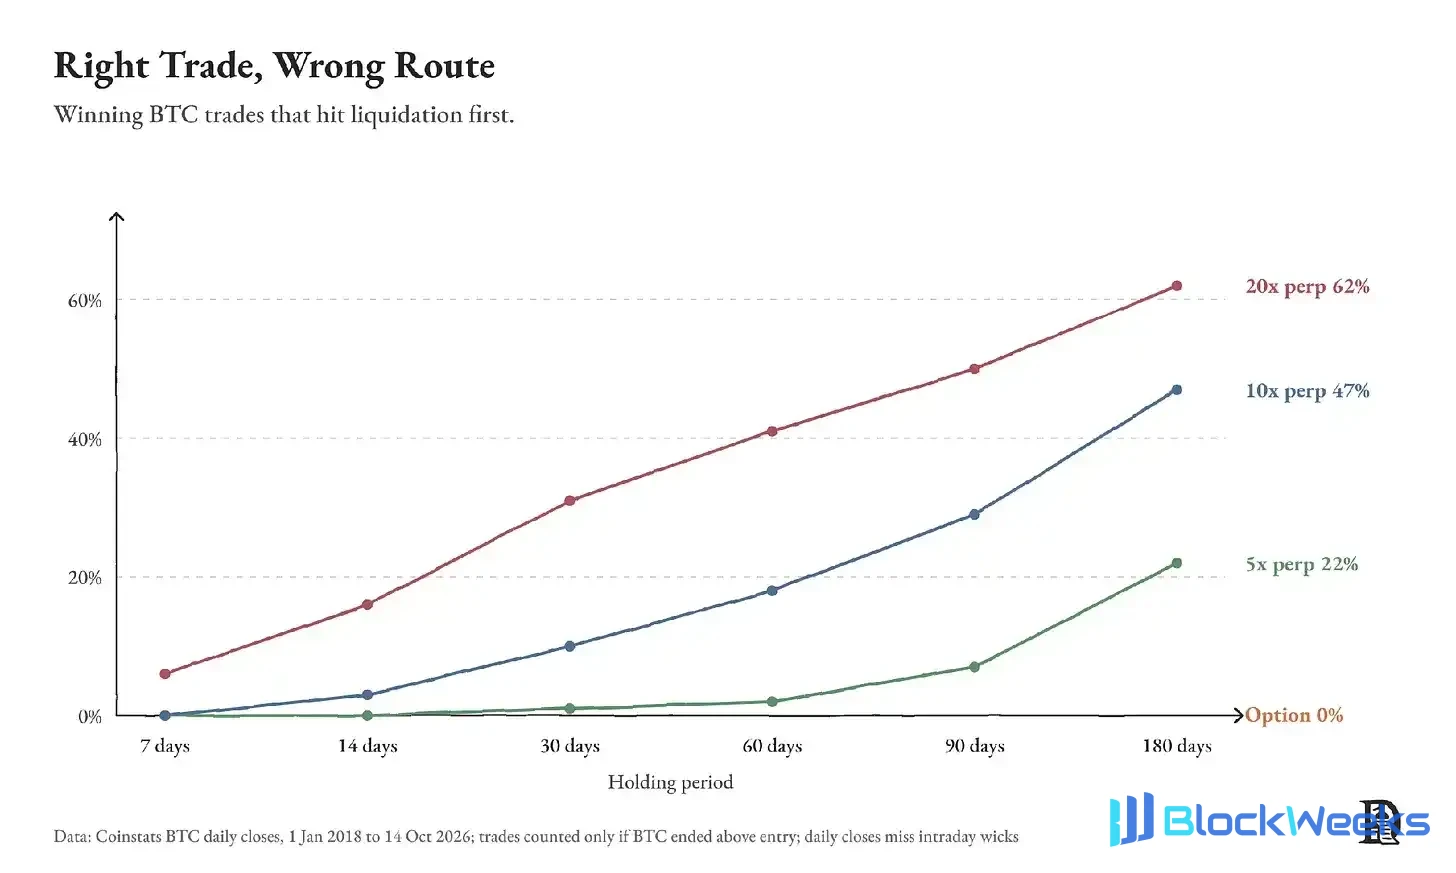
A 10x perp has a 47% chance of being liquidated within 180 days, 29% within 90 days, and 18% within 60 days. Buying an option covering the same time window will not be liquidated before expiry. Daily closing prices also miss intraday wicks, so the real probabilities may be higher. In March of this year, we wrote in Bringing the World On-Chain: directional capital overwhelmingly chose perps. This is still true for trades measured in hours. But the longer a judgment takes to play out, the more likely a perp is to be stopped out or liquidated.
We reviewed October 10, 2025. At 12:00 UTC, we opened three $1,000 BTC long positions. The first was a 10x perp; the second was a 30-day call bought with the same $1,000; the third was still that 10x perp, but paired with a 7-day put with a strike 5% below the entry price, with the premium paid out of that $1,000.

The perp position was liquidated at 21:14. The call fell to $181 at the low, but was back above $800 in less than an hour. The put cost $52 and kept this 10x long alive through the crash. We repeated this test across eight assets using Deribit prices, and the results were consistent.

On small coins, this protection costs $250 to $340 out of $1,000, because their option pricing embeds much higher volatility.
Everything Is on the Menu
Traditional finance and crypto are borrowing each other's things in three ways.
First, traditional finance is importing crypto's tools. CME now trades crypto futures and options around the clock. Hyperliquid's perp prices appear on the Bloomberg Terminal, and Hyperliquid's policy department and trade.xyz have already filed with the SEC for rules on pre-IPO perps. Polymarket launched perps in September for users outside the United States.
Second, crypto is importing traditional finance's assets. On Hyperliquid, you can trade the S&P 500, Nvidia, gold, and crude oil as perps at any time of day. In Everything is a market, we said that Treasuries, stocks, compute, and attention will all trade on-chain. Anyone in the industry can see that every important asset will eventually come on-chain. And perps are exactly how all of this is happening. On March 23, trade[XYZ]'s WTI and Brent crude perps together traded $2.3 billion in a single day. There is now a perp tied to the hourly rental rate of Nvidia H100 GPUs, and another tied to a Pokémon card index. CME and ICE are waiting for CFTC approval to list compute futures.
As more tradable prices emerge, people will want different ways to trade them. Some may use GPU perps to bet on compute shortages. An AI startup with exposure to the same price may simply want to buy protection against higher bills next quarter.
Buying a call option lets the startup buy that protection for a known amount. If the rental rate rises above the agreed level, the option pays out. If the rate falls, the startup enjoys cheaper compute and loses only the premium. And the perp simultaneously gives the person who sold that option a tool they can use to hedge. Every new perp market opens up room for an options market right next to it.
Third, traditional finance's tools now serve crypto's own assets. In April, open interest in BlackRock's Bitcoin ETF options climbed to $27.6 billion, surpassing the open interest in BTC options on Deribit. In the same period, Coinbase acquired Deribit for $2.9 billion.
The same trading venue may eventually offer spot, perps, options, and binaries all at once, with underlyings ranging from Bitcoin to stocks to commodities. Whoever gets there first will capture most of the flow. We believe crypto starts ahead for two reasons.
Listing is a software decision. IBIT launched in January 2024, but its options didn't begin trading until November of that year, waiting for exchanges, clearinghouses, and the SEC to sign off one by one. Hypercall listed SpaceX options on June 3, 2026, nine days before SpaceX listed on Nasdaq, using Hyperliquid's pre-IPO perp as the reference price.
This market never closes. Hypercall lets you trade Nvidia and SpaceX options even on Sundays, because the perps used to hedge them also trade on Sundays. Spreads outside US stock market hours are 1.5 to 2 times wider. But traditional trading venues don't offer Nvidia options at all during that time.
The rise of perps is the best thing that could happen to onchain options, because perps are exactly where options sellers hedge. The deeper the perp market, the cheaper it is to sell options on top of it. Every new perp market is a potential options market.
Why onchain options never took off
Since 2019, dozens of protocols have tried to bring options onchain. Nearly all have shut down, pivoted, or have almost no volume. We went through them generation by generation in Trading Optionality; here's a brief version. Options are much harder to launch than perps, for three reasons.
Liquidity is fragmented across hundreds of order books per asset. BTC perps have only one order book. Deribit lists 884 BTC options across 11 expiries, and every single one must be quoted around the clock.
 Sellers can't hedge cheaply. Sellers must continuously trade the underlying to stay neutral, which requires a sufficiently deep market right next to it.
Selling ties up capital. Early protocols required sellers to lock up the maximum amount they could theoretically owe. Selling a $1,800 call on $110,000 BTC meant locking up $100,000 to earn 1.8% a month. No professional market maker would take that trade.
 Each generation solved one of these and stumbled on another. In May 2021, Hegic depositors lost most of roughly $80 million; over seven months, Lyra depositors lost 4.9% in the BTC pool and 17.6% in the ETH pool; PsyOptions shut down its product in June 2024.
 So why do market makers avoid it? Before retail arrives, most of the flow that hits a new venue's quotes comes from traders arbitraging its prices against Deribit. They only act when the new venue's quotes go stale, so even if the platform runs perfectly, market makers lose money on almost every fill. A platform has only two paths: pay the first market makers to absorb those losses, or bring them retail flow that doesn't exist yet.
How today's platforms solve it
The platforms that work today share the same basic design. Orders are matched offchain, so updating quotes costs nothing. Collateral, margin, and settlement stay onchain, so you always retain control of your funds.
But a better design still has to give a reason to sell. The strongest reason is a cheap hedge in the same account. Remember the seller who had to lock up $100,000 to sell a $1,800 BTC call?

A portfolio margin engine calculates the maximum possible loss across all positions and derives the required collateral from that. If the worst reasonable move is 15%, the seller only needs to post about $15,000 instead of $100,000. The premium is still $1,800, so the return on locked capital jumps from 1.8% a month to about 12%.
That's why we believe options will take off where perp liquidity already exists, and today that means platforms like Hyperliquid and Lighter. Options sellers on Hyperliquid get three things at once that other onchain venues can't put together.
The first is depth. Hyperliquid has the deepest perp order book onchain, and builder codes let any app plug into it.
The second is one account. A trader who sells a put can reuse the collateral to open a perp long, with spot, perps, and event contracts sharing the same risk engine. This is the most critical improvement over predecessors. The third is users, and platforms that hold liquidity, users, and distribution at the same time tend to retain the value they create.
Hypercall is the first options platform built on this foundation. A market maker who sells you an Nvidia call can buy an Nvidia perp on Hyperliquid in the same account, and that hedge reduces the margin required for the option. Its founder estimates that 10 to 100 times as many market makers quote perps as quote options. Hypercall gives this group of perp market makers a reason to quote options too.
Other platforms have each found different sellers.
 Derive (formerly Lyra) pays its sellers. In the year through October 19, it cleared about $18 billion in options notional, and FalconX is its only publicly named market maker. FalconX's funds stay with its custodian, and Derive represents that balance as a tradable token, so institutions can quote on-chain without moving collateral on-chain.
Paradex borrows its sellers. On September 15, it connected to Paradigm's network, which handles about a quarter of Deribit's block trades. Its daily options volume jumped from less than $3 million to $58.7 million within a week, but open interest fell from more than $250 million to about $96 million by October 14. The people doing block trades come for one trade, and then they leave.
Rysk turns holders into sellers. You deposit HYPE, BTC, or ETH, sell covered calls to whitelisted market makers, and receive the premium upfront. In the 30 days through October 14, it did $148 million in notional, but once the buyers of these calls capped their own exposure to HYPE, volume stalled.
The front ends built on top of these platforms hide the strike table entirely. Dream lets you top up with Apple Pay, pick a direction and position size, and then buys the options for you. Tacticalls, built on Derive, offers three-tap bets and copy trading. Simpler wrappers can pull users in. But when the order book underneath is empty, it cannot create a seller.

It's listed, but how much liquidity is there?
September 2026 was the best month ever for on-chain options. Notional roughly doubled to $5 billion, premium grew by a third to $85 million, and open interest peaked near $2.5 billion. That is still only about 7% of Deribit's volume that month. Most of it went through Derive.
 A platform that only sells cheap deep out-of-the-money contracts can pile up very high face value with very little capital turnover. Premium, the cash the buyer actually pays for the option, is the more reliable yardstick. By premium, Derive's share is even higher, above 90%.
 Most of Hypercall's notional comes from cheap deep out-of-the-money options on the S&P 500, bought as lottery tickets. Pink Brains found that on Hypercall, $1 of premium buys about $1,000 of face value, while on Derive it buys only about $50. Three reasons may explain the gap.
First, volatility. The S&P 500 moves about 16% a year, while BTC moves 43%, so its options are much cheaper.
Second, the contract itself. A short-dated call far from the spot price costs only a few tenths of a percent of face value.
Third, incentives. When Hypercall paid out $1,000 in HYPE per day, notional rose 50-fold while premium barely moved, suggesting traders were likely buying the cheapest contracts to collect the rewards. Derive is where traders pay for real options exposure.
Is Derive's book good enough? On the evening of October 19, we pulled every listed BTC and ETH option on Derive and Deribit, excluding deep out-of-the-money contracts and those expiring within three days. Deribit had both a bid and an ask on all 346 strikes included in the count. Derive had two-sided quotes on 206. Where Derive did quote, its ask was within 0.2% of Deribit's, and its bid-ask spread was about 3.8% of the option price, versus 2.6% on Deribit.
In Trading Optionality, published in July 2025, we found that Derive's spreads were often 2 to 5 times those of Deribit. Since then, that gap has narrowed significantly.
Outside BTC and ETH, it is a different story. Derive lists options on 12 assets, and we pulled every strike expiring on December 25 from its public API.
 PUMP, LIT, ADA, VVV, and CC had a combined 220 strikes for the December 25, 2026 expiry, and one quote. When we tried to buy a December PUMP call, the order took a long time to fill. Even where there are quotes, spreads widen quickly as you move away from the spot price. HYPE is the most liquid mid-cap asset on Derive, and it shows how quickly this happens.
 Every platform we checked showed the same situation. Aevo only quotes memecoin options through its OTC desk, and Dream moved its PUMP and LIT trading to a single OTC counterparty. Listing an option costs the platform almost nothing. Selling an option is both expensive and dangerous.
Time Left Until Expiry
In traditional markets, 88.65 billion options contracts were traded in 2025, versus 30.64 billion futures contracts. On-chain, in the 30 days ending October 19, 2026, options did $4.9 billion in notional volume, while perp DEXs did $627 billion. That's roughly 0.8%.

Most of us already hold options, we just don't call them that. If your mortgage allows early repayment, you hold a call against the bank. Insurance is a put. Employee stock options are calls paid out as salary. Each one corresponds to a specific need, and all of those needs exist in today's crypto market.
We don't expect on-chain options to reach the same proportion as traditional finance, because part of crypto's demand for options has already been met by other products. Prediction markets are selling binary versions, and now perp platforms are selling them too. On October 19, Lighter launched binary options on BTC and ETH.
Even so, on-chain options still have three blocks of demand:
Assets that traditional finance can't list quickly. HYPE, pre-IPO companies, GPU rental rates, and stocks and crude oil that trade on Sundays too.
Users that traditional finance can't reach. Anyone outside the US, anyone without a brokerage account, anyone who wants to trade with $1. We pointed to India's retail options culture in It's All Derivative—there, weekly options account for 95% of NSE volume.
Options embedded in other products. Downside protection attached to a perp, covered calls for treasuries, liquidation insurance for loans. On-chain, an option can be plugged into any application via an API.
Old Winners in a New Market
The simplest way to answer this question is to trace where the fees from an options trade go.
 Options platforms charge a small fee once when an option trades. The platform where the hedge is placed, on the other hand, charges repeatedly every time the market maker adjusts the hedge. That's why options boost perp volume. Deribit has over $2 billion in futures open interest, and much of it exists to hedge the platform's options. So we see three positions worth holding.
The landlord, such as Hyperliquid, holds the hedging market, the margin accounts, and the users, and HIP-4's binary contracts already share the same account. Its HIP-4 contracts are designed for "bounded option-like instruments," which means they could in turn eat Hypercall's own market. Either way, the hedging volume ends up on Hyperliquid.
The engine that facilitates options trading is an obvious bet. Derive has the deepest order book, a risk engine, a cohort of professional users, and, with V3, an API that others can build on. If wallets, vaults, and agents route their options flow through it, Derive becomes the backend for on-chain options. If not, it remains a venue sustained by subsidized liquidity with only one public market maker.
The block desk, such as Paradex, holds Paradigm's institutional flow. That's valuable for large trades, and the market makers who come for that flow also make the order book deeper, benefiting everyone.
Platforms that don't give sellers a way to hedge are already losing ground. While the category grew fourfold, Aevo's options business shrank by more than 90%. Isolated options products struggle to beat products that can be combined with other primitives like perps and spot. We'll likely see a similar adoption pattern for options as builder codes—one platform carries the liquidity, many frontends share it.
The market is already pricing in one of these outcomes. Citrini Research's "Breaking The Wall" portfolio allocates 10% to DRV, and DRV is up more than 1,000% this year. On October 22, DRV had a market cap of about $390 million, against net revenue of $486,000 in the 30 days ending October 20—about 66 times annualized revenue.
What would Derive need to grow into that? Assume on-chain options reach 5% of perp volume. Perp volume in October is expected to be about $660 billion. 5% is roughly $33 billion in options notional volume. If Derive keeps about 80% of notional share, at its roughly 1.1 basis point fee, that's about $35 million in annualized fees, equivalent to about 11 times fees at today's market cap. So DRV's price is betting that the whole category grows about sixfold while Derive holds share—and Hyperliquid, Lighter, and Paradex chase the same flow.
Putting Options into Liquidity Pools
Sellers don't all have to come from options platforms. Metric is a DEX whose active pools work much like Uniswap's concentrated liquidity. LPs place liquidity in bins (price ranges) above and below the current price, and earn the spread whenever traders use their bin. The difference is how the bin ranges are set. On Uniswap, LP ranges are fixed, and only trading can move the price, so LPs must constantly reset their ranges as the market moves.
On Metric, a curator plugs in a price provider, usually an oracle, and bins are set as percentage ranges around that reference price. The price moves, and the bins move with it. In the 30 days ending October 21, Metric did $4.4 billion in volume with about $12 million in deposits.
What if these pools quoted option prices? Metric's documentation lists Black-Scholes with a volatility input as one of the optional models for price providers. A curator could take a live volatility feed and price a tokenized ETH call.
Take an example: an ETH call with a $2,600 strike expiring October 30. Assuming ETH is around $2,430 with implied volatility near 50%, Black-Scholes gives a price of about $18. If ETH rises to $2,500, the same call is worth about $35, and all the bins shift up with it. And because Metric's pools are routed through aggregators like 0x, 1inch, CoW Swap, and PancakeSwap, traders can buy options tokens like any other token, using the swap frontend they already use.
The problem is that while this gives instant distribution, it's not capital efficient.
Every strike and expiry would be its own token and pool. For example, an ETH call with a $2,600 strike expiring October 30 pays holders the amount by which ETH exceeds $2,600 at expiry. The next expiry requires an entirely new set of tokens. Market makers on Deribit quote hundreds of instruments from a single margin account. On Derive, selling this $2,600 call under standard rules requires about $330 in margin, before accounting for hedging offsets. Selling a fully collateralized $2,600 call locks up 1 ETH (about $2,430) to earn $18. Each Metric pool also needs its own inventory, so five strikes times two expiries means ten separate pools of capital.
So the solution lies in who issues the token. Suppose Derive issues it. Derive already lets sellers post margin and hedge on perps, so if you sell that $2,600 call through it, you only need to put up about $330 instead of a whole ETH. Metric can then keep doing what it does best: pricing the token and putting it in front of traders.
The Options Version of Papertrade
Back to Papertrade. Using token incentives to subsidize losses quickly pulled in capital and traders. That's exactly what on-chain options lack. Options lack incentives for sellers.
So what would an options version of Papertrade look like? A house vault sells calls and puts at listed strikes. When an option expires worthless, its buyer mints house tokens in proportion to the premium they lost, and those who stake the tokens earn the house's surplus.
Option buyers usually lose money frequently. From January 2018 to October 2026, a buyer who bought a weekly BTC call with a strike price 10% above the market price lost the premium in 87% of the weeks. Papertrade itself is obviously the best candidate for having built it. The difference is: perpetual traders with higher leverage are usually liquidated by a very small fluctuation, while option buyers hold until expiration, so the market maker must charge a reasonable premium and cannot rely solely on liquidations to make money.
The problem is that a market maker selling calls will win small for several months, and then lose big all at once when the market moves sharply in either direction. I did a cold-start modeling using BTC history. A pool starts from zero and sells calls with a strike price 10% above the market price every week. In this simulation, the market maker collects an average premium of about $1,300 per $100,000 of BTC, pricing 50% above the average cost of these calls. In 12% of the weeks (57 out of 458 weeks), BTC closed above the strike price, and the market maker paid out an average of about $6,900. So the net is: the market maker collects about $1,300 per call and pays out an average of about $860, netting about $440.
 Over eight years, the market maker made money. But in March 2021, it owed winners an amount equivalent to 30 weeks of premium income. It did not clear the queue until April 2022. In its worst single week, it paid out about 20 weeks of premium income at once.
This design must shorten the queue to the minimum. Stakers who earn the market maker's surplus in good weeks should bear its losses in bad weeks, so that winners get paid on time instead of waiting in line. The market maker should also hedge on existing perpetuals. As BTC rises toward the strike price, it buys BTC perpetuals on Hyperliquid. So in a highly volatile week, the hedge can cover most of what it owes winners.
When I added daily hedging to the same simulation, the cost of the worst week dropped from 20 weeks of premium income to about 10 weeks, and during the 2021 rally that left winners owed 30 weeks of income, the pool never went into liability. Our article on parlays made the same point about prediction markets: someone must act as a central liquidity manager.
A second possible design is: the market maker does not only sell, but takes the opposite side of every trade—if a trader wants to sell, it buys; if a trader wants to buy, it sells. When buyers and sellers match, the market maker is flat and earns the spread, so it only needs to hedge and fund the unbalanced side.
The problem lies in the token. If losses on both sides mint tokens, a trader can buy a call in one account and sell the same call in another account, knowing that one side must lose. Tokens must be minted based on each account's net loss on a single expiration date, and the spread must be wider than the value of the token. This is similar to the practice today on Papertrade of partially hedging one's own position.
There is reason to believe that this round of on-chain options attempts may survive. Sellers have a deeper hedging market, better ways to use capital, and more paths to reach buyers. Incentives can help bootstrap it. And when rewards shrink and the market turns, whether sellers can earn enough to keep quoting remains an open question.
But the foundation is stronger than in previous attempts. If they hold, more traders will be able to put a price on how long they are willing to wait for a judgment to play out. Crypto has already made it easy to buy leverage. The next thing may be time.
Still waiting to be proven right,